 ultimate-guide
Verifiable ESG Data for Building Maintenance: 2026 Guide
Table of Contents
- Why Building Maintenance Data Fails ESG Audits
- What Makes ESG Data Verifiable in Facility Management
- Automated ESG Data Collection Tools for Building Maintenance
- Green Building Maintenance Best Practices That Generate Verifiable Data
- ESG KPI Verification and Assurance: How to Satisfy Auditors
- Manual vs. Automated Data Verification: A Cost-Benefit Analysis
- Building an Audit-Ready Data Checklist for Your Portfolio
- Frequently Asked Questions
Last Updated: September 29, 2026
Why Building Maintenance Data Fails ESG Audits
Most building maintenance records collapse under audit scrutiny for one reason: they were never designed to be verified. A work order marked "cleaning completed" tells an auditor nothing about energy use, water consumption, or how the activity was measured. Verifiable ESG data for building maintenance is the difference between a spreadsheet of claims and a defensible evidence trail.
What Makes ESG Data Verifiable in Facility Management
Verifiable ESG data is information that a third party can trace back to its source, confirm was collected without manipulation, and reconcile against a known standard. In facility management, that means every environmental metric links to a metered reading, a timestamped record, or an independently logged event.
The Four Pillars of Audit-Ready Data
Four conditions separate audit-ready data from self-reported figures:
- Traceability: every data point maps to its origin (meter, sensor, or log)
- Data integrity: records cannot be altered after collection without detection
- Consistency: the same method applies across every asset in the portfolio
- Third-party assurance: an external body can validate the numbers independently
Miss any one pillar and auditors treat the whole dataset as unreliable.
Data Interoperability: Connecting Legacy BMS to Modern ESG Platforms
The hardest gap to close is interoperability. Many commercial towers run building management systems installed a decade ago, speaking protocols that modern ESG platforms do not natively read. The fix is a middleware layer that translates BMS output into structured, timestamped data streams. Without it, teams export CSV files by hand, a process that introduces errors and destroys the traceability auditors require.
Automated ESG Data Collection Tools for Building Maintenance
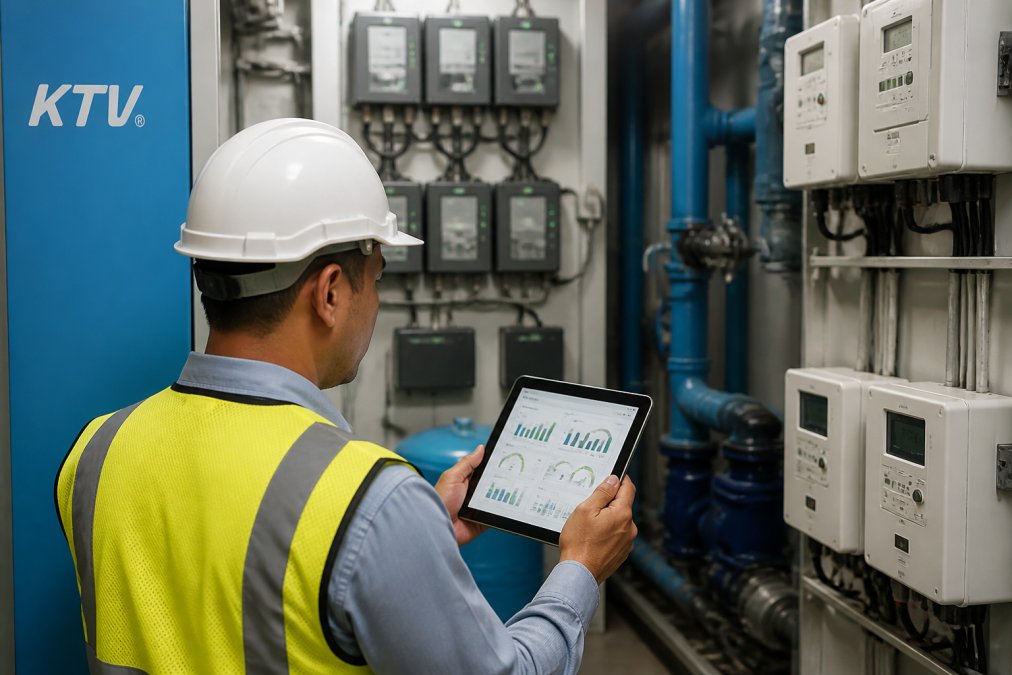
Automated collection tools remove the human transcription step that breaks data integrity. A common approach is to pair smart meters with software that logs readings automatically and pushes them into a central ESG platform.
Smart Metering and Energy Consumption Tracking
Smart metering is the backbone of verifiable environmental metrics. Interval meters capture energy consumption, water usage, and sometimes waste volumes at fixed intervals, producing a continuous record rather than a monthly estimate. For carbon emissions reporting, this granularity matters: auditors can reconcile total consumption against utility bills and flag discrepancies before they become findings.
Green Building Maintenance Best Practices That Generate Verifiable Data
Green building maintenance best practices only count as ESG evidence when each activity produces a structured record. Drone-based facade cleaning, for example, generates a digital log of surfaces treated, time on site, and method used, all timestamped and exportable. Chemical-free processes also reduce the waste management and water usage footprint that frameworks track.
| Practice | Data Generated | ESG Metric Supported |
|---|---|---|
| Drone facade cleaning | Timestamped activity log | Operational efficiency, safety |
| Smart metering | Interval consumption data | Energy, water usage |
| Digital work orders | Completion + method records | Governance, traceability |
| Waste tracking | Volume + disposal records | Waste management |
ESG KPI Verification and Assurance: How to Satisfy Auditors
ESG KPI verification and assurance is the process where an independent body tests whether reported metrics are accurate and complete. It is not a single event, it is a sequence of evidence tests, and knowing the sequence is what lets facility teams prepare rather than react.
The Two Levels of Assurance
Practitioners generally work to one of two engagement types:
- Limited assurance: the assurance provider performs analytical review and targeted sampling, then states that nothing has come to their attention suggesting the data is materially misstated. This is the more common starting point for building-level environmental metrics.
- Reasonable assurance: a deeper, higher-cost engagement where the provider gathers sufficient evidence to express a positive opinion. Investors increasingly push for this on headline carbon and energy figures.
The practical difference for a facility team is the volume of source documents an auditor will request. Limited assurance may sample a handful of meters per asset; reasonable assurance typically expands the sample and tests the controls around the data pipeline itself.
What Auditors Actually Test
A typical assurance workflow on building maintenance data runs through four tests:
- Completeness, does the reported total cover every in-scope asset, or have some meters been quietly excluded?
- Accuracy, can the reported figure be traced to a meter reading, sensor log, or signed service record?
- Cut-off, are readings assigned to the correct reporting period, or has a December meter read been pushed into January?
- Consistency of methodology, is the same emission factor, boundary, and estimation method applied across the portfolio?
Materiality and the Evidence Hierarchy
Auditors do not treat all evidence as equal. A metered interval reading from a calibrated device sits near the top of the hierarchy. A utility invoice is strong but lags real-time consumption. An internally estimated figure based on floor area or operating hours sits at the bottom and is usually only acceptable for small, immaterial line items.
Where Building-Level Data Feeds Corporate Disclosure
Building-level metrics rarely stand alone. They roll up into corporate sustainability statements, and the frameworks that govern those statements shape what auditors expect at the asset level.
Preparing the Evidence Pack
Teams that pass assurance fastest assemble a single evidence pack per reporting period: meter inventories, calibration certificates, utility bill reconciliations, middleware data-flow documentation, and the methodology statement. When every figure in the report can be traced to an item in that pack, the auditor's sampling exercise becomes a confirmation rather than an investigation.
A Practical Pre-Assurance Sequence
- Confirm the reporting boundary and list every in-scope asset
- Reconcile metered totals against utility invoices for the period
- Document the emission factors and estimation methods used
- Freeze the dataset and log any post-period adjustments
- Run an internal sample trace on the highest-contribution assets
- Hand the auditor the evidence pack and the methodology statement together
That sequence turns assurance from an annual scramble into a repeatable process, and it is the same discipline that makes the audit-readiness checklist in the next section usable.
Manual vs. Automated Data Verification: A Cost-Benefit Analysis
Most guides stop at 'automate for accuracy.' That is not a business case. A cost-benefit analysis has to separate the one-time build cost from the recurring operating cost, and then compare both against the cost of getting it wrong.
The Cost Structure of Manual Verification
Manual verification has almost no setup cost and a high, linear running cost. The recurring labor breaks into four activities:
- Exporting readings from meters, BMS, or utility portals
- Cleaning and reformatting the data into a reporting template
- Cross-checking figures against invoices and service records
- Rebuilding the evidence trail when an auditor requests a trace-back
The Cost Structure of Automated Verification
Automated collection inverts the profile. Setup cost is front-loaded, middleware integration, meter connectivity, platform configuration, and mapping each data stream to the correct ESG metric. Running cost is low and largely fixed: the system logs readings on a schedule, timestamps them, and stores them in an immutable record.
The Decision Threshold
A useful way to frame the choice is by portfolio scale rather than by preference:
| Portfolio profile | Manual | Automated |
|---|---|---|
| Single small building, few metrics | Defensible | Setup rarely justified |
| Several assets, multiple metrics | Error-prone, labor-heavy | Usually justified |
| Large portfolio, assurance required | Not defensible | Effectively mandatory |
The Hybrid Trap
The most expensive outcome is not choosing manual or automated, it is running both without reconciliation. When some assets report automatically and others are keyed in by hand, there is no single source of truth. Auditors test consistency across the portfolio, find that two assets were measured by different methods, and the inconsistency casts doubt on the entire dataset.
Where the ROI Actually Shows Up
The financial case for automation is usually made on labor savings, but that understates it. The larger return comes from three places:
- Avoided assurance findings, each finding triggers remediation, re-testing, and management time
- Faster reporting cycles, automated data is available continuously, not assembled quarterly
- Operational savings surfaced by the data, interval metering exposes after-hours consumption and equipment faults that manual monthly reads never reveal
Building an Audit-Ready Data Checklist for Your Portfolio
Use this checklist before any assurance engagement:
- Every environmental metric traces to a metered or logged source
- Data collection is timestamped and tamper-evident
- The same methodology applies across all assets
- Legacy BMS data flows through a documented middleware layer
- Access controls and audit logs protect building-level data
- A named third party can independently validate the figures
- Records reconcile against utility bills and contracts
Data security and privacy belong on this list too. Building-level reporting often contains tenant-identifiable consumption patterns, so access controls and retention policies are part of audit-readiness, not an afterthought.
Frequently Asked Questions
What constitutes verifiable ESG data in facility management?
Verifiable ESG data is information that a third party can trace back to its source and confirm without relying on self-reported claims. In facility management, this means energy, water, waste, and maintenance records that are time-stamped, asset-linked, and generated by calibrated or certified systems. A drone cleaning report, for example, should include flight logs, before-and-after imagery, and surface area treated, so an auditor can match the outcome to the intervention. Without that chain of evidence, data stays self-reported and fails assurance.
How does autonomous drone technology improve ESG reporting accuracy?
Autonomous drones capture consistent, repeatable data on every flight because the route, speed, and sensors are controlled by software rather than human judgement. That removes the variability you get when different crews inspect or clean facades by hand. Each mission produces a digital record: time, location, area covered, and environmental conditions. Those records can be exported directly into ESG platforms, giving sustainability teams asset-level data that auditors can verify. The result is fewer gaps and less manual reconciliation at reporting time.
Why are building maintenance audits failing ESG standards?
Most failures come down to three issues: data gaps, inconsistent units, and no traceability. Maintenance teams often track work in spreadsheets or paper logs that cannot be linked to a specific asset or timestamp. When an auditor asks for evidence behind a carbon emissions figure, the trail goes cold. Another common problem is using estimated data for energy or water consumption instead of metered readings. Auditors accept estimates only with clear methodology, and many facilities do not document that methodology at all.
What are the key performance indicators for sustainable building maintenance?
The core KPIs include energy consumption per square metre, water usage per occupant, waste diversion rate, carbon emissions from maintenance activities, and maintenance cycle time. For exterior cleaning, you can also track surface area treated per litre of water or per hour, and the percentage of work completed without work-at-height incidents. These indicators matter because they connect operational activity to environmental outcomes. Choose KPIs that your team can actually measure with existing or easily installed metering infrastructure, then verify them through third-party assurance.
How can facility managers automate ESG data collection?
Start by identifying the data points you report most often: energy, water, waste, and maintenance events. Install smart metering on major consumption points and connect them to a data platform that logs readings automatically. For maintenance, use tools that generate digital records as a byproduct of the work itself, such as drones with flight logging or computerised maintenance management systems with mobile checklists. The goal is to remove manual entry so data is captured at the source, time-stamped, and ready for ESG KPI verification and assurance.
Who is liable if a drone damages a building during maintenance?
Liability depends on the contract and the operator's insurance coverage. Reputable providers carry aviation liability insurance and clearly state their responsibility for damage caused by equipment failure or operator error. Before signing, ask for the certificate of insurance, the coverage limit, and whether it covers third-party property damage. Also confirm the provider operates under the correct aviation permits. In Thailand, commercial drone operations require certification from the Civil Aviation Authority of Thailand, so verifying that the operator holds a valid certificate is a basic due-diligence step.
How do you handle weather delays or incomplete drone cleaning jobs?
A professional drone maintenance provider will build weather contingencies into the schedule and define what counts as a completed job. Ask for a clear scope: which facades, what percentage of surface area, and how completion is verified. Most providers will reschedule weather-affected work at no extra cost, provided the delay is outside their control. Get this in writing. If partial access is an issue, the provider should document the areas completed and return to finish the rest, with the data record reflecting exactly what was done.